
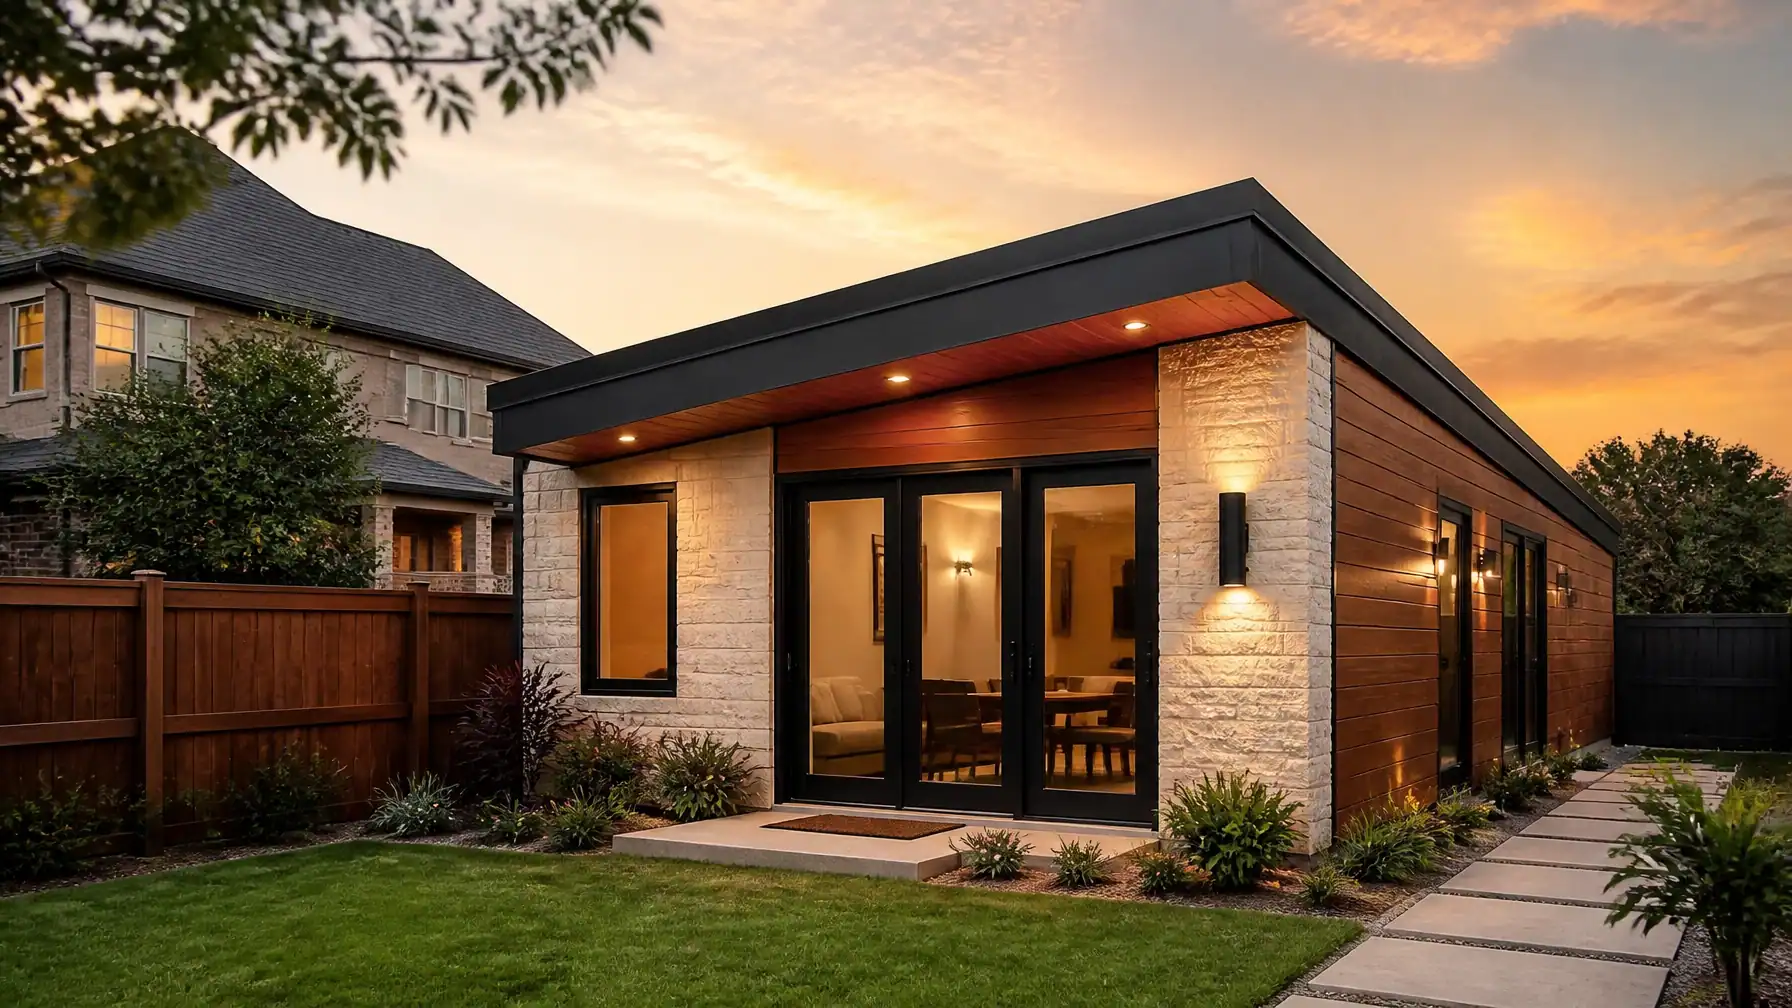
What if the space you plan to build could help support the financing required to build it? For many homeowners across Keller, Southlake, Fort Worth, and the broader North Texas Metroplex, that question has become far more relevant under recent lending updates. For years, an Accessory Dwelling Unit (ADU), mother-in-law suite, or income-producing secondary structure was often treated as a long-term value play rather than a practical path to mortgage qualification. That assumption has changed.
At PRO Construction, A Boomer Group Inc. Company, we help homeowners evaluate projects with both structural discipline and financial clarity. With Bruce Laing’s 25 years of local experience, we have seen how lending policy, site feasibility, and local approval standards can either protect your investment or complicate it. FHA Mortgagee Letter 2023-17, along with updated Freddie Mac guidance, has created a meaningful opportunity: in certain cases, lenders may count projected ADU rental income when determining whether you qualify.
That matters because this is not simply about adding square footage. It is about protecting your borrowing position, improving flexibility, and making careful property decisions that strengthen your legacy over time.
The FHA Game-Changer: Mortgagee Letter 2023-17
Until recently, if you wanted to build a guest house on your property in Denton County or Tarrant County, the projected rent from that unit was often ignored by lenders during the qualification process. You had to qualify based solely on your existing income.
Under the new FHA guidelines, that has changed. Here is how it works:
1. Counting Income Before a Tenant Moves In
If you are building a new ADU or purchasing a home with one, the FHA now allows actual or projected rental income to be counted as "Effective Income." If you don't have a rental history for the unit yet, lenders can use 75% of the appraised fair-market rent (as determined by an appraiser) to help you qualify.
2. The 30% Rule
There is a safeguard in place: the amount of ADU rental income used to qualify cannot exceed 30% of your total monthly effective income. This ensures that while the ADU supports your mortgage, your primary financial stability remains the foundation of the loan.
3. Owner-Occupancy is Key
To prevent these rules from being exploited by corporate investors, the FHA requires the property to be owner-occupied. This is a win for local families in Fort Worth and Grapevine who want to build a functional structure for a senior family member or a long-term tenant while maintaining their primary residence.

Freddie Mac: Another Financing Route Worth Understanding
While FHA guidance has received much of the attention, Freddie Mac also gives North Texas homeowners a workable framework when a conventional loan is the better fit. If you are comparing financing strategies, the standards are different from FHA, but they can still be highly useful when planned correctly.
- One-Unit Primary Residences: Freddie Mac permits ADU-related income on qualifying one-unit primary residences.
- Comparable Rentals: The lender will typically want more than a basic appraisal. You should expect a lease and an appraisal that reflects comparable ADU rentals in the local market. Our local project experience, including the workshop and patio at 6612 Rhea Ridge Dr, helps us guide homeowners toward realistic planning and presentation.
- Landlord Education: If you have less than one year of landlord experience, Freddie Mac may require a short landlord-education course. It is a modest requirement, but one that can provide useful protection for your investment decisions.
Why This Shift Matters for Your Property Strategy
Across Flower Mound, Denton, and surrounding communities, we see the same pressure points repeatedly: families need more flexibility, property owners want better long-term value, and financing rules often determine what is realistically possible. Whether the plan involves a garage conversion with living space, like our work on Belaire Drive, or a thoughtfully planned detached structure, the ability to count future income can materially improve the feasibility of the project.
Used wisely, these lending changes can help support a larger and better-planned scope of work, one that protects structural integrity instead of forcing compromises. We approach that responsibility seriously. From post-tension slabs to durable material selections, our goal is to build an asset that performs well over time, not a shortcut solution that creates future risk.

Navigating the Process with a Seasoned Local Team
Building an ADU involves more than good design. It requires disciplined attention to site feasibility, permitting, lender expectations, and local code requirements. Those details can become burdensome quickly, which is why we carry that weight on your behalf. From early planning with our design partner, Boomer Group, through inspections and construction oversight, we work to keep the process orderly, transparent, and far less stressful for you.
Key Financial Requirements to Remember:
- Reserves: Most lenders will require at least two months of PITI (Principal, Interest, Taxes, and Insurance) reserves to be held in your account after closing.
- Zoning: The ADU must be legally permissible. As guest house builders in Denton County, we handle the heavy lifting of verifying local zoning laws to ensure your build is fully compliant.

Protecting Your Legacy
At PRO Construction, we’ve been "DRIVING QUALITY HOME" since EST. 2001. Our top 1% BuildZoom ranking reflects more than reputation; it reflects Bruce Laing’s 25 years of local experience and a long record of honest, steady work across North Texas. We also value the strength of seasoned local partnerships, including Gus Moreland at First United Bank, Builders FirstSource, ProSource, and Sherwin-Williams, because strong outcomes depend on strong teams. When you choose to build an ADU, you are not simply adding square footage. You are working to maximize property value and create a flexible structure that can serve your family well for years to come.
Whether your goal is to support a returning college student, create a safer option for aging parents, or generate reliable rental income that helps offset your mortgage, current FHA and Freddie Mac rules have made this a much more practical conversation for many homeowners in 2026.
Key Takeaways for Homeowners
| Feature | FHA (ML 2023-17) | Freddie Mac |
|---|---|---|
| Income Cap | 30% of total qualifying income | Based on DTI/Stability |
| Projected Income | 75% of appraised market rent | Lease + Comparables required |
| Property Type | 1-unit owner-occupied | 1-unit primary residence |
| Experience | No specific requirement | Education course if < 1 year |
| Reserves | 2 months PITI often required | Varies by lender |
Let’s talk about your project.
A successful ADU project begins with a clear conversation about your goals, your budget, your property constraints, and the financing path that makes the most sense. We’ve managed everything from custom kitchens and sliders at 2502 Hillside Ct to more demanding structural improvements throughout the Metroplex.
Start a conversation today. We would be glad to show you how disciplined planning, transparent communication, and local experience come together in a well-managed build.
PRO Construction
A Boomer Group Inc. Company
Phone: 817-372-0211
www.proconstructiontx.com

Frequently Asked Questions
Can I use ADU income for a cash-out refinance?
Generally, no. Under current FHA rules, ADU rental income cannot be used to qualify for a cash-out refinance. It is primarily intended for purchases and standard "no-cash-out" refinances or 203(k) rehabilitation loans.
Does the ADU have to be detached?
Not necessarily. An ADU can be detached, attached to the primary dwelling, or even a converted space like a basement or garage, provided it has separate ingress and egress and meets local habitability standards.
Is financing available for the construction itself?
Yes. We offer flexible financing options and can help you navigate how programs like the FHA 203(k) can be used to fund the construction of your new ADU or the renovation of an existing structure.